Accounting for every side of real estate. For agents, property managers, landlords, and investors.

978-986-9154 Free 30-minute consultation

Property management trust accounting services

Outsourced property management trust accounting that keeps owner and tenant funds separate, reconciled three ways every month, and documented so you’re prepared if your state real estate regulator reviews your records.

Trust money is the money you can’t get wrong

Property management trust accounting is the part of your books where a mistake isn’t just an accounting error. Every dollar in your trust account belongs to someone else: an owner’s rent and reserves, a tenant’s security deposit, a prepayment you haven’t earned yet. If those balances don’t tie out, you are the one answering to the owner, the tenant, and potentially your state’s real estate regulator.

Most trust problems don’t start with anything dramatic. A receipt gets posted to the wrong property. A vendor bill is paid before the owner’s rent clears, driving that owner’s balance negative. Management fees sit in trust for a few months. A deposit is refunded but never cleared from the tenant’s ledger. Each one is small; together they make a trust account that nobody can fully explain. We find those problems, fix them, and put a monthly process in place to keep them from coming back.

Our property management trust accounting services

Monthly trust account reconciliation (three-way)

A trust account reconciliation that only compares the bank to your books isn’t enough. Every month we perform a full three-way reconciliation: the adjusted bank balance, the trust account balance in your books, and the sum of every individual owner and tenant ledger must all agree. When they don’t, we trace the difference to the transaction that caused it and correct it. You get a complete reconciliation package for your records.

Owner funds vs. operating funds

Your management company’s money and your clients’ money must stay separate. We record management fees, leasing fees, and other charges when they’re earned, prepare the transfer from trust to operating for your approval, and flag any company expense paid from trust so it can be corrected right away. Every movement between accounts is documented, so the line between owner funds and operating funds is visible to anyone who reviews your books.

Security deposit accounting

Security deposits are a liability, not income. We record each deposit against the tenant who paid it, track it through the lease, and handle move-out deductions and refunds so the tenant’s ledger closes at zero. Each month we reconcile the total deposit liability to the funds held, whether you keep deposits in the main trust account or in a separate deposit account. Where your state requires interest on security deposits, we track what each tenant has earned.

Negative balance and exception review

A negative owner balance means another client’s money paid that owner’s bills. We flag negative balances, unidentified deposits, stale outstanding checks, and unapplied receipts every month, with a recommended fix for each, so exceptions get resolved instead of rolling forward.

Trust account cleanup and catch-up

If your trust accounts haven’t reconciled in months, or you’ve inherited a portfolio, changed software, or lost a bookkeeper, we start with a cleanup. We work forward from the last point the account agreed, document every adjustment, and hand you a reconciled starting point.
Commingling risk: how it happens without anyone intending it

Commingling (mixing company money with client money) is one of the most common trust account problems property managers run into, and it rarely comes from bad intent. It looks like earned management fees left in trust, an operating bill paid from the trust account “just this once,” owner rent deposited into the operating account by mistake, or company funds added to trust to cover a shortage. Some states allow a limited amount of company money in trust to cover bank charges; beyond that, the rules are strict.

Our job is to make sure each of those situations is caught and corrected in the month it happens, with a clear record of what moved, why, and when.

Preparing for a state real estate commission audit

In many states, the real estate commission or licensing department can examine a broker’s trust account records, either on a routine schedule or in response to a complaint. Requirements differ from state to state, including how often you must reconcile, whether deposits must be held separately, and what records you must keep and for how long. Always confirm the details with your broker of record or attorney. What examiners generally look for is consistent:

  • Reconciliations completed on schedule, with all three balances agreeing
  • No negative owner or tenant ledger balances
  • Security deposits fully accounted for, tenant by tenant
  • Clear separation between trust funds and the company’s operating funds
  • Supporting documentation for receipts, disbursements, and transfers

We work to keep your records in that condition every month, so an audit request becomes a matter of handing over files rather than rebuilding a year of reconciliations under a deadline.

Why property managers choose JAV for trust accounting

  • Real estate specialists. We focus on real estate accounting, so trust reconciliations, owner ledgers, and deposit tracking are everyday work for us, not something we learn on your account.
  • Senior oversight. Your trust accounting is led by a founder with more than 30 years of accounting experience. She was formerly a partner at an accounting firm that served mortgage companies, where she led the accounting and consulting department.
  • Works with your current setup. We can work in your existing systems or help you move to new ones, either alongside your staff or as your entire accounting function.
  • Documented, not just balanced. Every reconciliation, adjustment, and transfer is supported, so you can show your work to an owner, your tax preparer, or an examiner.

Trust accounting is one part of the full property management accounting service we provide, including owner statements, distributions, and the monthly close for your management company. If you own rentals rather than managing them for others, see bookkeeping for rental property, or work with a dedicated real estate bookkeeper. You can also browse all of our real estate accounting services.

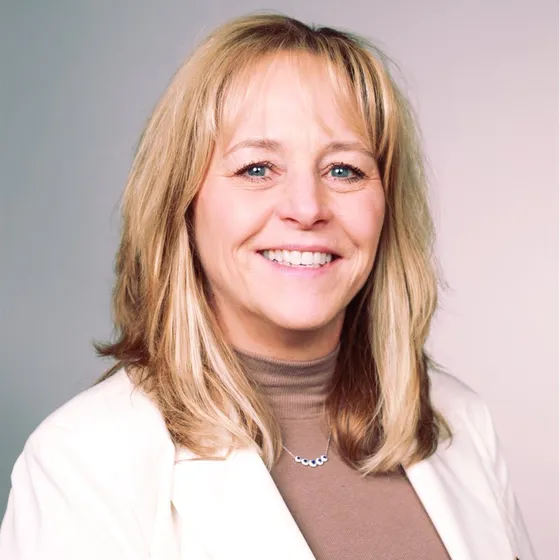
Susan Volpe, founder
Susan Volpe Founder

Why JAV Real Estate

I’ve spent more than 30 years in accounting. Earlier in my career I was a partner at an accounting firm that served mortgage companies, where I led the accounting and consulting department.

That work taught me what real estate books demand: detail down to the individual property, careful handling of money that belongs to other people, and reconciliations that are right every single month. I hold every client’s books to that standard, whether you manage properties for owners, own a few rentals, or sell homes for a living.

Susan Volpe, Founder

  • 30+ years in accounting
  • Former partner at an accounting firm for mortgage companies
  • Led an accounting & consulting department
  • Real estate and construction experience

More about Susan and how we work →

From first call to books you trust

  1. 01 Day 1

    Free 30-minute call

    We learn your properties, entities, software, and what’s not working. You leave with an honest read on your books, even if you don’t hire us.

  2. 02 Onboarding

    Cleanup & setup

    We bring the books current, build a real estate chart of accounts, set up per-property tracking, and reconcile every account back to the bank.

  3. 03 Every month

    Monthly close

    Transactions recorded, bank and trust accounts reconciled, and statements produced, plus a short summary of what changed and what needs your attention.

  4. 04 Year-end

    Tax-season handoff

    Your CPA, or one of our CPA partners if you need one, gets an organized, reconciled package to prepare your return.

Start with step one

Frequently asked questions

What is property management trust accounting?

Property management trust accounting is the recordkeeping for money a property manager holds on behalf of others: owner rents and reserves, tenant security deposits, prepaid rent, and other client funds. It covers depositing those funds into a trust (escrow) account, recording every receipt and disbursement against the right owner or tenant ledger, keeping that money separate from the management company’s own funds, and reconciling the account every month.

What is a three-way reconciliation?

A three-way reconciliation proves that three numbers agree as of the same date: the trust bank balance (adjusted for outstanding checks and deposits in transit), the trust account book balance in your software or ledger, and the total of every individual owner and tenant ledger balance. A two-way bank reconciliation can balance even when some trust money isn’t assigned to anyone. The third leg confirms that every dollar belongs to a specific owner or tenant, and reviewing those individual ledgers each month is what catches one owner’s money covering another owner’s bills.

How often should trust accounts be reconciled?

Monthly is the common standard, and many states require trust accounts to be reconciled at least that often. Requirements vary by state, so confirm yours with your broker of record or attorney. We reconcile every month, after the bank statement closes, so differences are found while they are still easy to trace.

What counts as commingling in a property management trust account?

Commingling generally means mixing the management company’s own money with client funds. Examples include leaving earned management fees in trust, paying company expenses from the trust account, and depositing owner rent into the operating account. Some states permit a limited amount of company money in trust to cover bank charges. The exact rules differ by state, which is why we document every transfer between trust and operating accounts.

Can you help us prepare for a real estate commission trust account audit?

Yes. We help you get audit-ready: current three-way reconciliations, owner and tenant ledgers that tie out, a security deposit liability that matches what you hold, and supporting documentation organized by month. If your records are behind, we catch them up first. Interpreting your state’s regulations and communicating with the regulator remain with your broker of record and legal counsel.

Our trust account doesn’t reconcile. Where do you start?

We start with a cleanup. We go back to the last month the bank, the books, and the ledgers agreed, then work forward, identifying unrecorded transactions, misposted receipts, negative owner balances, stale outstanding checks, and deposits that were never tied to a tenant. You get a written list of every difference and how it was resolved, followed by a monthly process to keep the account reconciled.

Get your trust accounts reconciled and audit-ready

Book a free 30-minute consultation. We’ll walk through how your trust, deposit, and operating accounts work today and what it takes to get them reconciled every month.